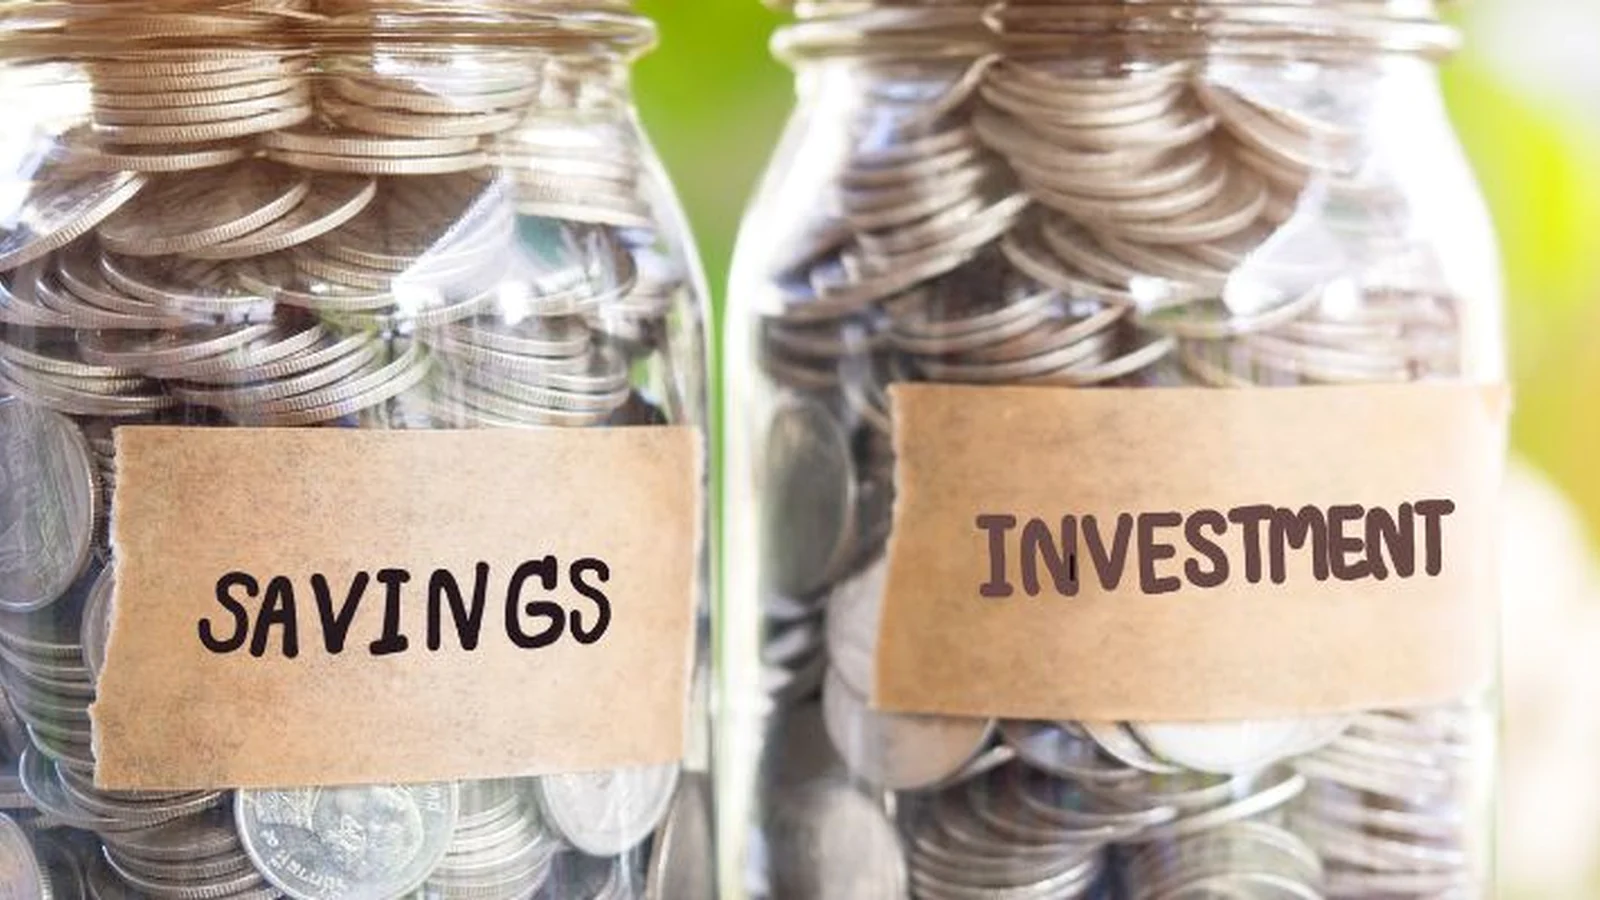
Saving can be difficult when one income supports goals in two countries. The first step is to separate emergency needs, family support, property goals and long-term savings so they do not compete in one account.
Give each savings goal a name
An emergency fund, Kenya trip, property deposit and retirement contribution are different goals with different timelines. Naming them makes tradeoffs visible.
Automate what can be automated
Regular transfers immediately after payday can reduce the temptation to save only what remains at the end of the month.
Budget family support intentionally
If remittances are a recurring responsibility, include them in the monthly plan rather than treating each transfer as an unexpected emergency.
Review the system, not only the balance
A savings plan should change when income, exchange rates, family responsibilities or major goals change. Revisit it periodically and seek qualified financial advice for investment decisions.
General educational information only; personal financial and investment decisions should be reviewed with appropriately qualified professionals where needed.
Building stronger connections across borders?
Continue with practical DLX resources for diaspora family life, identity, community and cross-border decisions.